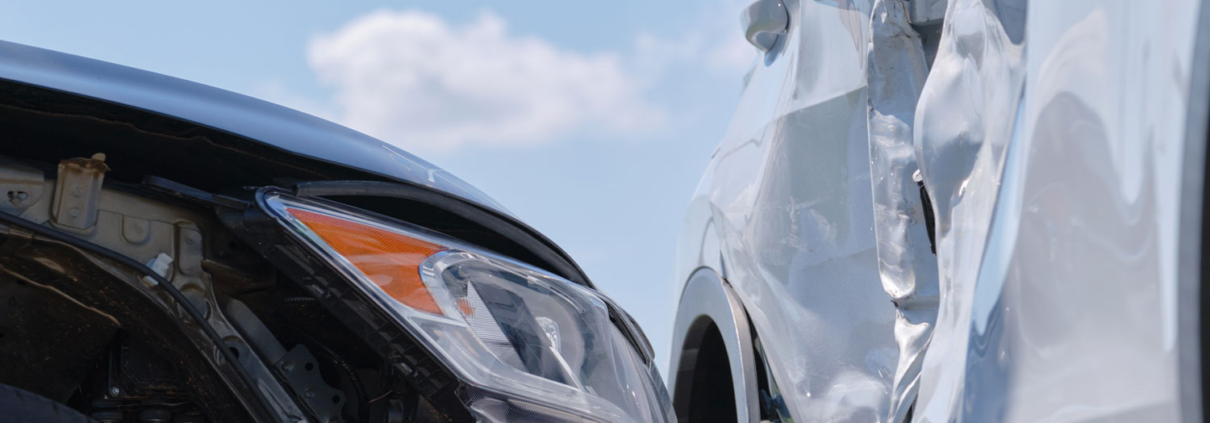
No one wants to think about having a car accident, discovering storm damage to their home, or experiencing a loss at their business. But when something unexpected does happen, knowing what to do next can make an already stressful situation much easier to navigate.
Insurance is there to help you recover from covered losses, but the claims process can feel overwhelming if you’ve never been through it before.
Whether you’re dealing with an auto accident, property damage, or another insured loss, here are a few important steps to keep in mind.
First, Make Sure Everyone Is Safe
Before worrying about insurance, prioritize safety.
If you’ve been involved in a car accident, move to a safe location if possible and call 911 when necessary. If your home or business has been damaged by a fire, severe storm, fallen tree, or another event, don’t enter an area that could be unsafe.
Once any immediate danger has passed, you can begin documenting what happened and determining your next steps.
Document the Damage
Photos and videos can be extremely helpful during the claims process.
For an auto accident, consider documenting:
- Damage to all vehicles involved
- The accident scene
- License plates
- Road or weather conditions
- Any other relevant details
For damage to your home or business, take photos or videos of the affected areas and damaged belongings before beginning cleanup when it is safe to do so.
If you need to make temporary repairs to prevent additional damage, such as covering a broken window or placing a tarp over a damaged area, keep receipts for materials or services and document the damage beforehand when possible.
Gather Important Information
Having the right information readily available can help make the claims process smoother.
Depending on the type of claim, this might include:
- Your insurance policy information
- The date and approximate time of the incident
- Photos and videos
- Contact information for others involved
- Police or incident reports
- Receipts or records for damaged property
For auto accidents, exchange insurance and contact information with the other driver, but avoid making statements about fault at the scene. Stick to the facts when speaking with law enforcement and your insurance company.
Report the Claim Promptly
Once you’re safe and have gathered the necessary information, contact your insurance company or agent to report the loss.
You’ll typically be asked to provide details about what happened and the damage you’ve experienced. Depending on the situation, an insurance adjuster may then inspect the damage, request additional documentation, and explain the next steps.
Keep in mind that every claim is different. Your coverage, deductible, policy limits, and the circumstances surrounding the loss will all affect how your claim is handled.
Understand Your Deductible
Your deductible is the amount you’re responsible for paying toward a covered loss before insurance pays according to the terms of your policy.
Ideally, you should know your deductibles before you ever need to file a claim.
Take a few minutes to review your auto, homeowners, and other policies so you know what you would be responsible for if something happened tomorrow.
Keep Records Throughout the Process
Claims can involve multiple conversations, documents, estimates, and receipts. Keeping everything organized can save you time and frustration.
Consider keeping a folder—digital or physical—with:
- Your claim number
- Adjuster contact information
- Photos and videos
- Repair estimates
- Receipts
- Copies of emails or other correspondence
If you have questions along the way, don’t hesitate to ask. Insurance can be complicated, and you shouldn’t feel like you have to navigate the process alone.
Be Prepared for Severe Weather in the Upstate
October may bring cooler temperatures to Greenville and the surrounding Upstate, but severe weather can happen throughout the year.
Storms, high winds, heavy rain, hail, and fallen trees can all result in unexpected property damage. Having an up-to-date home inventory and knowing where to find your insurance information can make a big difference if you need to file a claim.
It’s also important to understand what your policy doesn’t cover. For example, standard homeowners insurance generally doesn’t cover damage caused by flooding from rising water, which typically requires separate flood insurance.
Don’t Wait Until a Claim to Understand Your Coverage
One of the best times to learn about your insurance is before you need to use it.
Understanding your deductibles, coverage limits, and exclusions ahead of time can help eliminate surprises when something goes wrong.
If it’s been a while since you reviewed your policies, Edwards Insurance can help.
Contact Edwards Insurance today to schedule a complimentary insurance review. Our team can walk you through your current coverage, answer your questions, and help make sure you’re prepared if you ever need to file a claim.
When the unexpected happens, knowing you’re properly protected can make the road forward a little easier.